By Jasmine Carter · Staff Writer
Published · Updated
Answer in brief
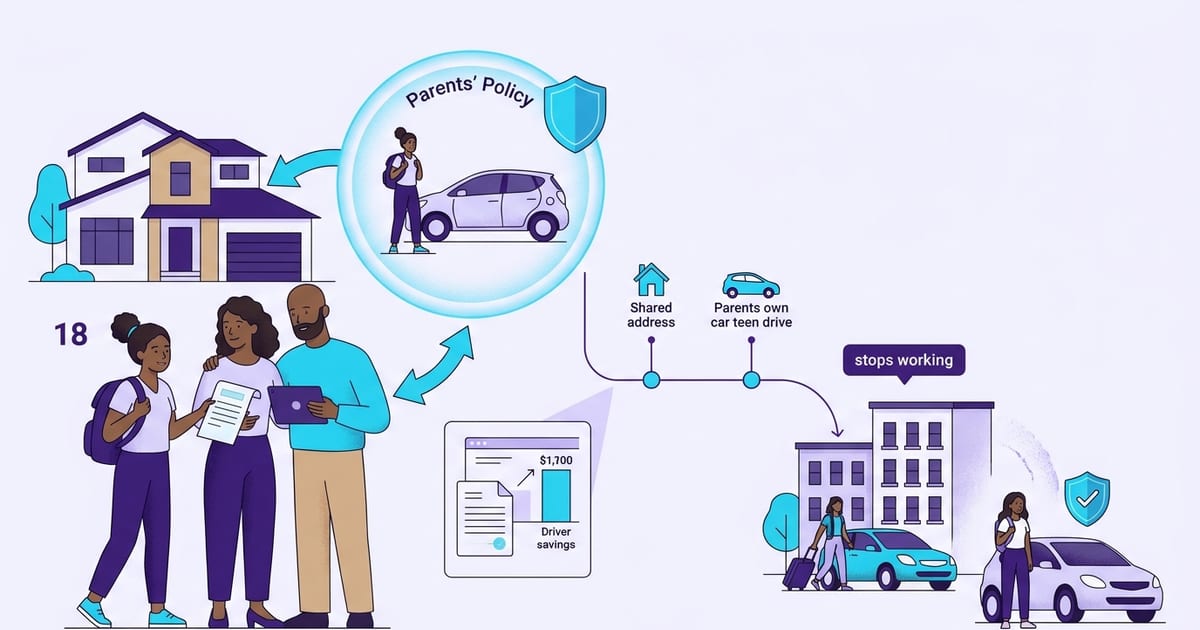
An 18-year-old can stay on a parent's policy as long as they live at the same address (or are away at school with the family home as permanent residence) and, with most insurers, the car is titled to a household member. It is usually 40–60% cheaper than a separate policy because the young driver inherits multi-car and bundling discounts and is rated as an occasional driver on a family vehicle. It stops working when the 18-year-old moves to their own permanent address or when the insurer requires the vehicle's title holder to be the named insured.
Eligibility
| Situation | Can stay on parents' policy? |
|---|---|
| Lives at home, drives family car | Yes |
| Lives at home, owns car titled in own name | Often, if the insurer allows; some require own policy |
| Away at college, permanent address at home | Yes—ask about the distant-student discount if no car at school |
| Moved out to own apartment | No—separate policy required |
| Married or has own household | No |
Why it is cheaper
A household policy shares multi-car and multi-policy discounts, benefits from the parents' longer history, and lets the insurer assign the 18-year-old as an occasional driver of the lowest-value car rather than the principal driver of their own. A separate policy starts with none of that.
The disclosure rule
Any licensed driver living in the household must be listed or formally excluded. An 18-year-old who lives at home and is not on the policy is a misrepresentation risk for the whole family. If they truly never drive the family cars, a named-driver exclusion is the proper route—but it means no coverage if they ever do.
Quote finder
Find auto insurance quotes that fit your situation
When to move off
When you move out permanently, or when you buy a car and the insurer requires you to be the named insured. Ask the family insurer for a quote first—continuity with one company helps—then compare. See own policy.
Entries in this guide
Specific questions answered in more depth.
Questions & answers
Can I be on my parents' insurance if I own my car?
Many insurers allow it if you live at home; some require the title holder to be a named insured. Ask.
Does going to college mean I have to leave the family policy?
No, if your permanent address is still the family home. Ask about a distant-student discount if you leave the car at home.
How much does adding an 18-year-old cost?
Typically $1,400–$2,600 a year on a family policy.
Terms used in this guide
- Household member
- A person living at the insured address. Licensed household members must be listed on or excluded from the policy.
- Named insured
- The person who owns the policy and signs the contract. At 18 you can be a named insured; some insurers require the vehicle's title holder to be one.
- Distant student discount
- A discount for a student at school 100+ miles from home without a car, who drives only during visits.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Graduated licensing laws by state — Insurance Institute for Highway SafetyIndependent researchState-by-state learner, intermediate and full-licence ages, night-driving and passenger restrictions.
- Facts + Statistics: Teen drivers — Insurance Information InstituteStatistical dataCrash and fatality statistics for drivers 16–19 and graduated licensing context.
- Fatality facts: Teenagers — Insurance Institute for Highway Safety (2024)Statistical dataFatal crash rate per mile driven for 16–19-year-olds is just over 3 times the rate for drivers 20 and older (2022 travel data); all-severity crash rate is over 4 times; risk is highest at 16–17.
- Drivers in fatal motor vehicle crashes by age, 2023 — Insurance Information Institute (2025)Statistical dataFatal-crash involvement per 100,000 licensed drivers: 42.40 (16–20), 35.34 (21–24), 28.97 (25–34), 24.18 (35–44), 21.70 (45–54), 19.45 (55–64), 15.44 (65–74), 16.63 (75+).
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- Auto insurance for teen drivers — Insurance Information InstituteConsumer guidanceAdding a teen to a parent's policy versus a separate policy; good-student and driver-training discounts; vehicle choice.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
Getting Your Own Car Insurance Policy at 18
How an 18-year-old buys a policy independently: legal capacity, documents needed, coverage to choose, payment plans, and how to keep the price down.
Guide
How Much Car Insurance Costs at 18
What 18-year-olds pay for car insurance on their own policy and on a parent's, why 18 is priced the way it is, and what changes by 19, 21 and 25.
Guide
Car Insurance for 18-Year-Olds Going to College
Insurance when an 18-year-old leaves for college—taking a car or not, distant student discounts, out-of-state rules, and staying on the family policy.